Webinar
Webinar recording: EU free trade agreement, relocation pressure, and China+1: How is India's role changing for European supply chains?
For years, European manufacturers have been searching for a reliable alternative to China. India is increasingly moving into focus, yet the decision to establish a second procurement market is rarely based on solid data. This webinar provides an assessment of how advanced the country actually is, what the EU free trade agreement means for procurement calculations, and which steps are realistic.
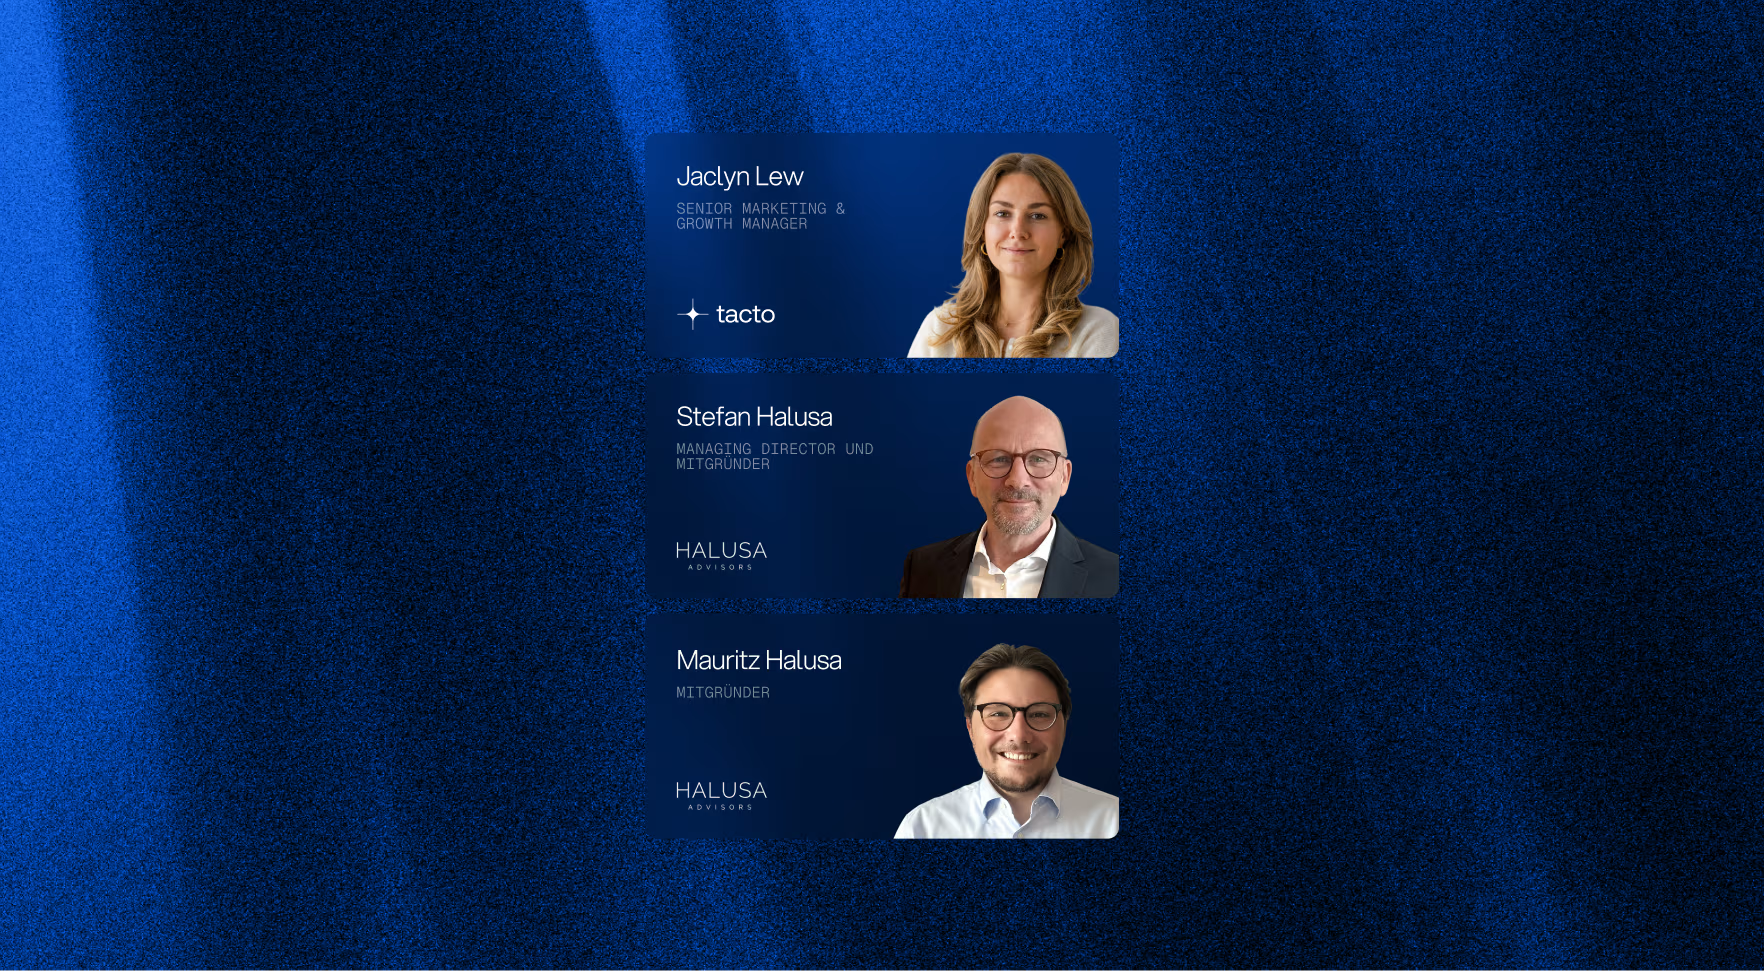
Stefan Halusa (Managing Director and Co-Founder at Halusa Advisors) and Mauritz Halusa (Co-Founder at Halusa Advisors) join Jaclyn Lew (Senior Marketing and Growth Manager at Tacto) to provide an overview of India as a procurement and production hub. Halusa Advisors supports industrial companies in making decisions between Europe and Asia, drawing on over 20 years of operational experience on the ground in India, Korea, and Japan.
India as a Business Location: Domestic-Driven Growth Instead of an Export Model
With a population of 1.42 billion and a median age of 29, India is the world's fourth-largest economy. Its GDP stands at approximately 4.1 trillion US dollars and grew by 7.6 percent in the 2025/26 fiscal year. Based on this trajectory, India is expected to overtake Germany as the third-largest economy within this decade.
The source of this growth is crucial for understanding the context. Unlike China's rise, it is not import-intensive but rather driven by domestic demand. The government's guidelines, "Make in India" and "Viksit Bharat 2047," aim to foster local production and build internal capacity. For European manufacturers, this means that India is not looking for a mere extension of its workbench, but for partners who will build value creation locally.
Omni-Alignment: India's Foreign Policy Follows Its Own Interests
The foreign policy vision of "Vishwamitra," or "Friend of the World," describes a position that deliberately avoids taking sides. India is simultaneously active in BRICS, the QUAD, the G20, and the SCO, working with all blocs in its own interest. Four principles shape this stance: strategic autonomy, "Neighbourhood First," "Act East" and "Link West," and its role as a bridge-builder.
For companies planning for the long term, this independence is a double-edged sword. It makes India less susceptible to the conflicts that strain European supply chains. However, it also means that the country does not automatically align itself with European positions on geopolitical issues. Furthermore, there is a volatile neighborhood characterized by border conflicts and political instability in several bordering states.
Sourcing Status Today: Presence, Exchange Rates, and the Cost Leverage of the Agreement
Around 2,000 German companies are active in India, with about 800 of them maintaining their own production facilities. Supplier and partner networks are therefore already in place. German imports from India grew by 12.5 percent in 2025, primarily distributed across chemical products (20 percent), clothing and footwear (15 percent), machinery (13 percent), and electronics and electrical engineering (11 percent).
Two cost factors are converging. The rupee has depreciated by around 18 percent against the euro over the past twelve months, making purchasing in euros noticeably cheaper. Skilled professionals with five to ten years of experience cost between 15,000 and 30,000 euros per year, though with an annual increase of 9 to 10 percent. The EU free trade agreement will also lower European import duties on Indian goods, which previously averaged 5.1 percent. Several questions remain: the agreement has not yet been ratified, a separate investment protection agreement is missing, and several sectors are excluded or remain contentious, including dairy, grain, CBAM, automotive, and non-tariff trade barriers.
From procurement to local manufacturing. The impact of India's industrial policy
India's industrial policy utilizes production incentives totaling around 26 billion US dollars, targeting electronics, semiconductors, pharmaceuticals and active ingredients, automotive parts, solar energy, and batteries. Indian suppliers are scaling accordingly; the target for electronics and components is 500 billion US dollars in manufacturing value by 2030, and 350 billion for the textile sector. This creates a two-sided effect: sourcing in India is becoming more attractive, while at the same time, European manufacturers will increasingly encounter Indian competitors in global markets. This is particularly evident in pharmaceuticals and active ingredients, where India, as the world's third-largest producer, already represents a direct alternative to China.
Conclusion
For European manufacturers, India is not a short-term alternative location, but an option that requires lead time and patience. The free trade agreement improves cost calculations, but it does not replace the need to vet the supplier base or decide whether pure sourcing, relocated final assembly, or your own production fits your business model. If you wait until the agreement is fully in force to get started, you are already behind.
Stefan Halusa and Mauritz Halusa from Halusa Advisors, together with Jaclyn Lew from Tacto, analyze how India's role in European supply chains is changing. The recording covers India as a business location, the country's foreign policy positioning, the current sourcing status of German companies, and the concrete consequences of the EU free trade agreement for tariffs and landed costs.