Blog
The American Reindustrialization: A Once-in-a-Generation Opening for Procurement
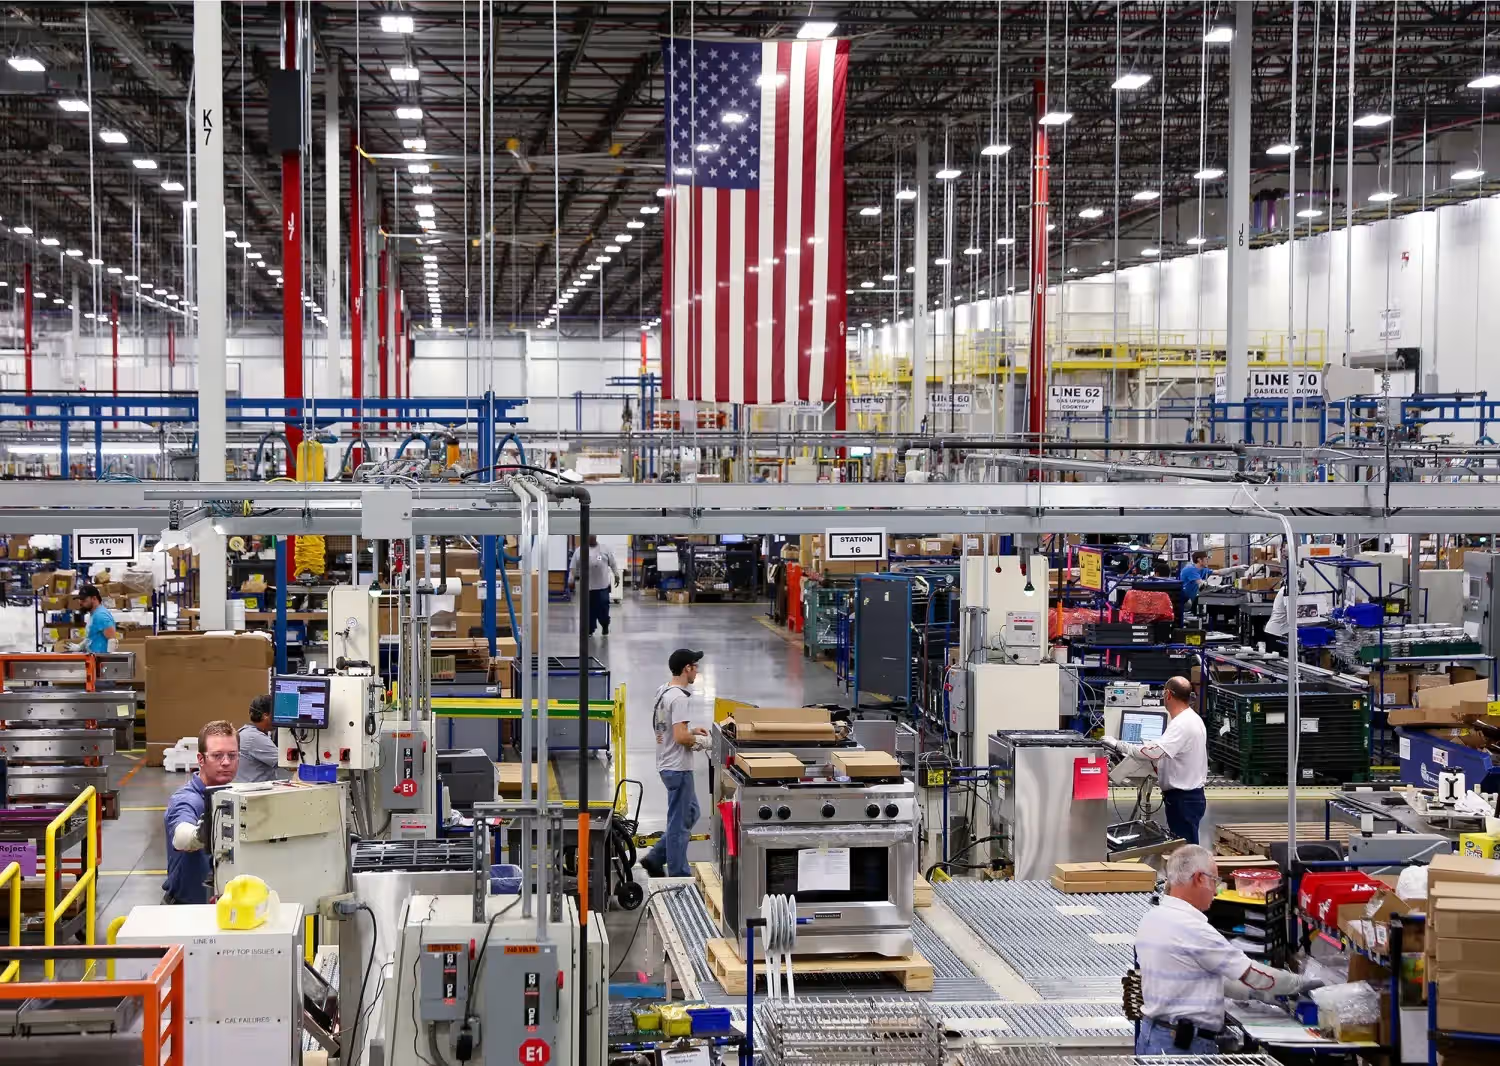
American industry is being rebuilt. Capital is pouring into factories, steel, autos, semiconductors and critical inputs at a pace nobody has seen in decades. Vice President JD Vance calls it a manufacturing renaissance, with billions moving into production capacity and industrial power coming back to US soil. Secretary of State Marco Rubio has made the same case from the other side, arguing that America made a historic mistake when it gave up its ability to build at home, and that Washington is now moving hard to rebuild it.
Through it all, American manufacturers never stopped building. Across decades of offshoring and economic downturns, they kept plants running, trained workers, and held supply chains together. The opportunity now is to build on that foundation, with more investment, stronger domestic supplier networks, and better tools for the people doing the work.
Your supply base is about to change, and procurement gets first shot at it.
1. The starting position
Zane Hengsperger wrote a great piece recently on rebuilding American industry. Worth your time. The numbers in it set the stage.
In 2000 the US produced roughly 25% of global manufacturing value added. China sat at around 6%. By 2023 those positions had flipped: China near 29%, the US around 17%. ITIF and CSIS estimates land in the same range, though methodologies differ.
None of that happened by accident. It came out of thousands of deliberate decisions. So it can be decided differently.
Look at Shenzhen. A fishing village in 1980. Today it ships more electronics than the entire United States. A CAD file becomes an injection-molded prototype there in 48 hours. In the US the same cycle takes six weeks and four vendors.
The advantage comes down to three things: density, speed, and the status attached to building physical things. All three are copyable. That is the good news.
Now look at where those six weeks actually go. Finding suppliers. Qualifying them. Coordinating them. Almost none of it is machining.
2. Reshoring is a supplier qualification project
The headlines are about factories. The work lands in your vendor files.
Bringing a part, an assembly or a whole category back to North America takes four things.
- Suppliers who can actually do the work. The standard to aim for: need eight parts from eight different processes, source all eight on US soil. Today that test fails almost everywhere. That is the gap to close.
- Qualification at speed. Every new supplier brings fresh audits, certificates and capability assessments. No quality history yet. You build it.
- A real view of cost. Reshored parts rarely come with a clean benchmark. You need a cost model built from material and process inputs.
- Clarity on inherited dependencies. China refines roughly 90% of global rare earths. Every F-35 carries around 920 pounds of them. A US line fed by a Chinese input two tiers down still carries the original exposure.
All four are procurement work. Every one of them is winnable.
3. Where programs stall
A common reason reshoring programs stall: procurement cannot answer basic questions fast enough.
Which parts are single-sourced from Asia? Which suppliers are already qualified for a comparable process here? What did we pay, what should we pay, what moved in the material index? Which certificates expire this quarter?
On Excel and email, every one of those is a two-week project. Multiply by a few hundred parts. Reshoring turns into a standing agenda item that never ships.
Closing that gap takes three things, and each one shows up in the P&L.
- One place for supplier and part data. Answer the questions above in minutes instead of weeks. Speed decides how many categories you can realistically move this year.
- A named owner with real time. Reshoring loses to the day job whenever it competes for the same hours. Categories move when someone owns them and has the capacity protected to do the work.
- Market data wired in. Material indices, price benchmarks and risk signals put evidence behind every negotiation. That is where the savings show up.
4. Point the technology at the floor
Here is where the US has a real edge. China built physical capacity first and is layering software on top. The US leaned the other way, putting more of its weight behind the software layer. That balance is shifting back now. And it left the country holding world-class software, AI and robotics talent, ready to be aimed straight at the factory floor.
The same edge applies upstream. Run a reshoring program on 2005 procurement processes and it crawls, whatever the capital behind it. Modern supplier management changes the pace:
- Supplier evaluation and categorization running continuously and automatically.
- Certificates and documents read and checked digitally.
- Cost models built from material and market data, so a domestic quote gets judged on its merits.
- Early warning on dependencies and compliance exposure, ahead of a stoppage.
This is the layer we work on at Tacto: an AI-supported procurement platform for industrial companies. Agents take the operational work off the desk so buyers get their hours back for decisions. Lower material costs and less manual effort both land in margin.
Conclusion: the window is open now
As domestic capacity grows, procurement gets more options. Which ones make commercial sense depends on cost, quality, capacity and the dependencies behind each supplier.
Policy will not answer that for you. The answers arrive one qualified supplier, one closed data gap, one rebuilt cost model at a time.
Build that capability this year and the reindustrialization push works in your favor. Start now.
Want to see what modern procurement looks like in practice? Book a 20-minute walkthrough of the Tacto platform.
Reindustrialization is landing in procurement before it lands anywhere else. Reshoring a part, an assembly or a whole category is a supplier qualification project: new sources to find and qualify, cost models to rebuild from scratch, and inherited dependencies two tiers down that a US line does not remove. This piece lays out where those programs stall, what procurement needs in place to move at the pace of the capital, and why the American software advantage belongs on the factory floor.